Critical metal + Nevada + buyer interest: Why things are getting exciting now — $EGMCF / $EMR


$30 million transaction history. Partners include Rio Tinto, Ivanhoe Electric, and Agnico Eagle. Market capitalization: just under $7.5 million (fully diluted). New York Canyon is being actively marketed – NDAs signed, several interested parties.

Dear readers,
Imagine this: A single ongoing deal at one company is already worth almost as much as its entire market capitalization. At the same time, NDAs have been signed with several interested parties for a copper project in Nevada – a country that has just declared copper a strategically critical metal. And the market? It had n't even registered this news in after-hours trading on Friday . That could change as early as Monday.
We're talking about Emergent Metals Corp. (WKN: A3DHBC | ISIN: CA29103R1055) , a Canadian microcap that, since 2020, has generated around USD 30 million in transaction value with a capital investment of approximately USD 7 million – through deals with Rio Tinto, Agnico Eagle, and Ivanhoe Electric. Its current market capitalization is USD 7.5 million. The gap between intrinsic value and valuation has rarely been so wide.

The dark secret of the mining sector – and how clever investors can avoid it.
Anyone who invests in mining stocks knows the pattern: A junior explorer presents stellar drilling results, the stock rises – and then falls back to its starting level over several months. Because the truth about the sector is as simple as it is brutal: Around 90% of all exploration projects never make it to production. Nine out of ten projects never become the hoped-for success.
The risks are manifold: disappointing drilling results, delayed or denied permits, financing bottlenecks, political instability in the project countries, management missteps, and sometimes – as in the case of Vizsla Silver in early 2026 – even criminal violence in the project region, causing a stock to plummet by over 50% within hours.

So how do smart investors navigate this minefield? The answer: They look for companies with alternative business models – those that participate at the right points in the value chain without bearing the biggest risks.
Emergent Metals Corp. (WKN: A3DHBC) goes a step further than classic royalty companies – with a model that is almost unique in this form in the mining sector.
The A&D model: Mine flipping according to the private equity principle
The concept is familiar from the real estate industry: buy a property in need of renovation cheaply, upgrade it, and sell it for a higher price. Emergent Metals has transferred precisely this principle to the mining sector – the A&D model: Strategic Acquisitions & Divestitures.
The model operates in three phases:
Phase 1 – Strategic Purchase:
Emergent identifies undervalued resource projects in prime jurisdictions and acquires them at discount prices – often outside the bidding market, thanks to CEO David Watkinson's 40-year network in Nevada and Quebec.
Phase 2 – Value Enhancement: Geological reinterpretation of historical data, geophysics, sampling, AI-supported resource modeling – the projects are enhanced for potential buyers.
Phase 3 – Monetization: Sale, joint venture, option or royalty deal to mining companies that are looking for exactly these kinds of advanced projects.
The average holding period is only 3 to 5 years – a fraction of the 10 to 20 years it takes for the traditional path from exploration project to producing mine. Permitting processes in Nevada alone take around 7 years. Emergent will be long gone before that even begins.

The result: Since 2020, Emergent Metals Corp. (WKN: A3DHBC) has generated approximately USD 30 million in transaction value with a capital investment of only about USD 7 million – in the form of cash, shares, work commitments, and royalty payments. Completed transactions with Rio Tinto (Kennecott), Agnico Eagle (O3 Mining), which was acquired by Agnico Eagle, Ivanhoe Electric , and Lahontan Gold demonstrate that this model is also accepted by the industry's major players.

Why Nevada and Quebec? The best mining locations in the world.
Emergent Metals Corp. (WKN: A3DHBC) operates exclusively in Nevada (USA) and Quebec (Canada) – two jurisdictions that rank 1st and 15th among the world's most attractive mining regions according to the Fraser Institute Survey 2025.
Nevada is historically THE gold state of the USA: 225 million ounces of gold have been mined here to date. In 2024, approximately 70% of total US gold production came from Nevada. The legal certainty, infrastructure, and mining-friendly regulatory environment make the state a preferred location for majors like Rio Tinto, Ivanhoe Electric, and Agnico Eagle – and therefore also for Emergent as a sales partner.
Quebec is almost on par with Nevada: Approximately 25% of Canada's gold production comes from the province. Quebec actively promotes the mining industry through tax breaks. Those with advanced projects there already enjoy a valuation premium compared to riskier jurisdictions.

The portfolio: Eight projects, four royalties – and one deal larger than the market capitalization
Emergent Metals Corp. (WKN: A3DHBC | ISIN: CA29103R1055) currently holds eight projects in its deal portfolio and four royalty interests – a total of 12 assets. By comparison, junior explorers with a similar market capitalization typically own only one or two projects, often without any track record.
Golden Arrow (Nevada) – The ongoing deal
Golden Arrow is the flagship project of the A&D model. The approximately 10,000-acre property in Nye County, Nevada, has – according to a press release – a measured and indicated resource of 296,500 ounces of gold and 4.0 million ounces of silver , supported by over 200,000 feet of historical drilling and 34 identified exploration targets.
The final purchase agreement with Fairchild Gold was signed on March 24, 2026. The transaction includes:
$250,000 non-refundable deposit (already paid)
$350,000 cash
12.5 million Fairchild shares at closing, currently valued at approximately USD 800,000 (as of April 25, 2026).
Senior Secured Note of USD 3.5 million at 8.5% p.a. (escalating to USD 5.0 million in the 5th year)
0.5% NSR royalty, which Emergent retains permanently.
The total value of this transaction is estimated at USD 6 to 7 million – non-dilutive, without issuing a single new share. For comparison, the total market capitalization of Emergent Metals Corp. (WKN: A3DHBC) was recently only around USD 7.5 million (fully diluted). A single deal thus represents almost the entire company value – and is already underway.
New York Canyon (Nevada) – The Copper Wildcard: Latest Update

From an upside perspective, New York Canyon is possibly the most exciting asset in the portfolio – and has just received an important update.
First things first: Emergent Metals has signed non-disclosure agreements (NDAs) with several interested parties and is actively marketing the project for sale, option, or joint venture. CEO David Watkinson confirms: The project has the right profile for junior and mid-sized companies – precisely the target group currently seeking strategically important copper properties.
The approximately 6,800-acre area comprises 21 patented and 320 unpatented claims in Nevada and has an exploration history with the biggest names in the industry:
Kennecott Exploration (Rio Tinto) invested USD 6.7 million in exploration (2020–2023) and confirmed copper mineralization.
Ivanhoe Electric optioned the project for USD 2 million and conducted further fieldwork in 2024/25.
Both majors declined to extend their options after the initial phase – simply because the project was too small for their scale, not because of geological problems.
The geological conditions are promising: The South Block hosts three known copper targets – Longshot Ridge, Copper Queen, and Champion. A 1979 Conoco report documented 142 million tonnes at Copper Queen alone, grading 0.35% copper (this resource was prepared prior to the adoption of NI 43-101, has not been verified by a Qualified Person, and is treated by the Company as a historical resource; see the press release dated May 28, 2019, for further details) .A 2010 NI 43-101 report estimated an indicated resource of 16.3 million tonnes, grading 0.43% copper, at Longshot Ridge (this is considered a historical resource under NI 43-101 and has not been reviewed or verified by a Qualified Person; see the press release dated May 19, 2019, for details). Kennecott (Rio Tinto) had one of the project's historically most important drill holes, MN-42, re-analyzed using modern laboratory methods. The result: A copper grade of 0.341% was confirmed over a length of 399 meters – a solid value demonstrating that the deposit remains economically viable even by today's standards ( see press release dated October 4, 2021 for details ).
Crucial to the timing: Copper was recognized as a critical metal by the US Department of Energy in 2023 and has been officially on the USGS list of Critical Minerals since 2025 – with high supply chain risk. According to the Fraser Institute, Nevada will be the number one jurisdiction worldwide for mining investments in 2025. A copper project in Nevada, with confirmed mineralization by Rio Tinto and Ivanhoe, actively marketed with signed NDAs – this is a constellation that deserves attention.
Casa Berardi South (Quebec) – 29,000 acres next to a $593 million mine
Emergent Metals Corp. (WKN: A3DHBC) holds 208 claims on approximately 29,000 acres in Quebec's Abitibi Gold Belt – directly south of and adjacent to the former Casa Berardi mine, which has produced over 2.4 million ounces of gold since 1988. Hecla Mining recently sold this mine to Orezone Gold for up to USD 593 million in cash, shares, and other consideration . The new owner will aggressively explore the area – and may require access to Emergent's adjacent land to do so. This presents a natural joint venture opportunity. Iamgold owns the property to the south.
Emergent has already completed approximately 6,000 meters of core drilling. A newly identified graphite target with a strike length of 10 kilometers adds an additional critical minerals component to the project.
Buckskin Rawhide East (Nevada) – Free Optionality
Emergent's "Buckskin Rawhide East" claims encompass a portion of a historic mine in Nevada with a reserve of 1.8 million ounces . The company leases the claims to the mine owner under a 20-year lease agreement for $10,000 annually ; in addition, Emergent receives $20 to $30 per ounce of gold mined on its property. The claims themselves have never been mined—a pure, unvalued potential asset in the portfolio.
The Royalty Portfolio: A Silent Treasure
Emergent Metals Corp. (WKN: A3DHBC | ISIN: CA29103R1055) has consistently incorporated royalty components into past project sales – thereby building a separate royalty portfolio alongside its deal portfolio. It currently comprises four investments:
NSR for a portion of Agnico Eagles Canadian Malartic Complex (producing mine)
NSR for a portion of Troilus Gold's Troilus mine (feasibility study stage)
NSR for a portion of Lahontan Gold's Santa Fe mine (PEA stage)
NSR for a portion of Lahontan Gold's West Santa Fe Property (exploration stage)
With the completion of the Fairchild transaction, a fifth royalty company will be added. Royalty companies have historically traded at valuation premiums on the stock market. We are not aware of any publicly listed royalty company with a market capitalization of less than $50 million. Emergent Metals Corp. (WKN: A3DHBC) is currently trading at only $7.5 million – and is already developing a royalty portfolio.
For comparison: Globex Mining (TSX: GMX) follows a similar project-generator model and is currently valued at around CAD 140–150 million. Emergent Metals is trading at a fraction of that.

Catalysts 2026: Why this autumn could be crucial
With a market capitalization of USD 7.5 million (fully diluted), it doesn't take a flood of events to move the share price. A single relevant news flow can be enough. And precisely this kind of news flow is expected for Emergent Metals Corp. (WKN: A3DHBC) in 2026 on several levels:
The Golden Arrow transaction with Fairchild Gold has been completed – cash, 12.5 million Fairchild shares and a $3.5 million note are being invested in the company.
Progress at New York Canyon – NDAs already signed, several interested parties actively under consideration; possible sale or joint venture deal
Assay results from Lahontan's drilling programs on the West Santa Fe property
Potential royalty buyback payments from existing NSR holdings
New acquisitions of projects are planned using the cash flow from the Golden Arrow transaction.
Lahintan's drilling program was also reported to interested investors at the Munich Capital Market Conference just last week:

The average daily trading volume is only around 400,000 shares. A single informed investor who correctly assesses the news situation can already generate significant movement here.
Management and investors: Who is behind Emergent Metals
The management team brings over 100 years of combined experience in the mining industry.
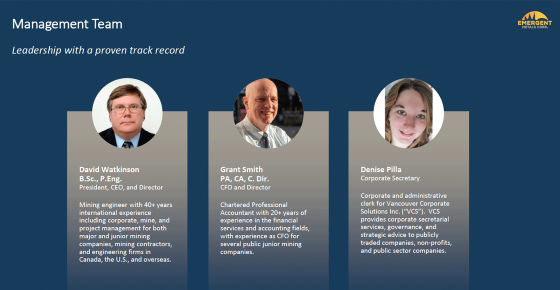
CEO David Watkinson has been in the mining industry for 40 years and knows the projects and owners in both Nevada and Quebec – a competitive advantage in project acquisitions that is virtually impossible to copy.
Managing Director Andrew MacRitchie is CFO of Skeena Gold + Silver, a gold producer with a market capitalization of over $6 billion. Director Robert Kiesman is also a member of Skeena's board of directors. Victor Contorie, who recently sold Northern Superior for $450 million, is a shareholder. Institutional investors recently invested CAD 550,000 above the market price – a clear signal.

Risks: What investors need to know
Emergent Metals Corp. (WKN: A3DHBC) is a speculative microcap company. The primary risk is that the Golden Arrow transaction with Fairchild Gold will not be completed (although Emergent would receive the property back in that case). In addition, the usual commodity price risks (gold, silver, copper) apply, as well as the risk of a reassessment of historical resource estimates and the general liquidity risk associated with low trading volume. Investors should only use speculative capital and limit their positions.
Conclusion: A basket of optionality – almost at no cost
Emergent Metals Corp. (WKN: A3DHBC | ISIN: CA29103R1055) is neither an ordinary explorer nor a traditional producer. It is a project accelerator with a proven business model, a diversified portfolio in prime jurisdictions, a growing royalty component – and a valuation that simply ignores all of that so far.
New York Canyon, with active NDAs and several interested parties, is poised for a potential breakthrough. Golden Arrow is practically a done deal. The royalty portfolio is quietly growing in the background.
The deals are in motion. The market hasn't noticed yet.
We wish you every success with your investments – and remain with best, but as always speculative, regards, your Mining Investor editorial team
Please also visit the Emergent Metals Corp. website at https://www.emergentmetals.com/ or review the company's filings on SEDAR+ ( https://www.sedarplus.ca/home/ ).

This promotional material was created by employees of Orange Unicorn Ltd. on April 26, 2026, and modified on April 28, 2026. In accordance with Section 84 of the German Securities Trading Act (WpHG), Orange Unicorn Ltd.'s activities are registered with the German Federal Financial Supervisory Authority (BaFin). This is paid advertising ; please note the information pursuant to Section 34b Paragraph 1 of the WpHG in conjunction with the German Financial Analysis Regulation (FinAnV). Payment is made exclusively by the advertising company and not by any third parties.
For the promotional reporting about Emergent Metals Corp., intermediaries, authors and publishers were paid by Emergent Metals Corp.
This constitutes a clear and unambiguous conflict of interest!
An intermediary holds shares of Emergent Metals Corp. and could sell them and profit from increased trading liquidity or a higher share price.
This constitutes a clear and unambiguous conflict of interest!
All publications, i.e. reports, presentations, announcements and contributions (“Publications”), serve exclusively for informational purposes and do not constitute a trading recommendation regarding the purchase or sale of securities or investment advice within the meaning of the German Securities Trading Act (WpHG).
The publications are not equivalent to professional financial analysis, but merely reflect the opinion of Orange Unicorn/mining-investor.com ("Publisher") or the authors of the publications ("Authors") working on its behalf. Every investment in the financial instruments presented here, such as stocks, bonds, derivatives on securities, etc. (collectively "Financial Instruments"), involves opportunities but also risks, including the possibility of total loss. For your own protection, buy/sell orders should always be limited. This applies particularly to the small- and micro-cap stocks discussed here, which are suitable only for speculative and risk-aware investors.
Every investor acts at their own risk. We provide marketing and advertising services exclusively and are not involved in company management or business decisions. The publisher and its authors assume no liability whatsoever for the timeliness, accuracy, completeness, or any other aspect of the quality of the publications.
Individual disclosures regarding the publisher's and authors' securities holdings and/or the remuneration of the publisher or authors by third parties related to publications will be expressly indicated in or below the respective publication.
Unless otherwise stated, the prices/rates for the financial instruments discussed in the respective publications are the closing prices of the previous trading day or more recent prices prior to the respective publication. General disclaimer: These publications are for informational purposes only.
All information and data in these publications originate from sources that the publisher and/or author considered reliable and trustworthy at the time of publication. The publisher and authors have exercised the utmost care to ensure that the data and facts used and underlying the publications are complete and accurate, and that the assessments and forecasts made are realistic.
However, the publisher assumes no responsibility for the accuracy, completeness, and timeliness of the information contained in the publications.
The publisher has no obligation to update the information.
He points out that subsequent changes to the information and opinions expressed in the publications by the publisher or author may occur. In the event of such subsequent changes, the publisher is not obligated to communicate or publish them.
The statements and opinions of the publisher/author do not constitute a recommendation to buy or sell any financial instrument. The publisher is not responsible for any consequences, especially losses, that may result from the use of the information and opinions contained in these publications.
The publisher and authors specifically do not guarantee that profits will be made or any price targets achieved as a result of acquiring the financial instruments that are the subject of the publications.
The publisher and author are not professional investment advisors. They work for third parties in connection with publications and receive payments from them for these publications, which may constitute a conflict of interest, and this is hereby expressly disclosed.
The information and opinions of third parties presented on the publisher's website, particularly in chat rooms, do not necessarily reflect the publisher's views. Therefore, the publisher assumes no responsibility for the timeliness, accuracy, completeness, or quality of this information. Copyright for individual articles rests with the respective author. Reprinting and/or commercial distribution, as well as inclusion in commercial databases, is permitted only with the express permission of the respective author or the publisher.
copyright
The copyright for each article belongs to the publisher. Reprinting and/or commercial distribution, as well as inclusion in commercial databases, is permitted only with the express permission of the publisher. Use of the publications is permitted for private purposes only.
Professional use is subject to a fee and is only permitted with the prior written consent of the publisher. Publications may not be transmitted, directly or indirectly, to the UK, the USA, or Canada, or to US citizens or any person residing in the USA, Canada, or the UK.
Imprint:
Information according to § 5 TMG:
Orange Unicorn Ltd
132-134 Great Ancoats Street
M4 6DE Manchester
Contact:
Telephone: +44 (0)161 768 0646
Email: info [at] mining-investor.com
Registered in England and Wales,
Registration number: 15974038
Supervisory authority: Companies House


Comments